By Rose Sklar, The Sklar Team
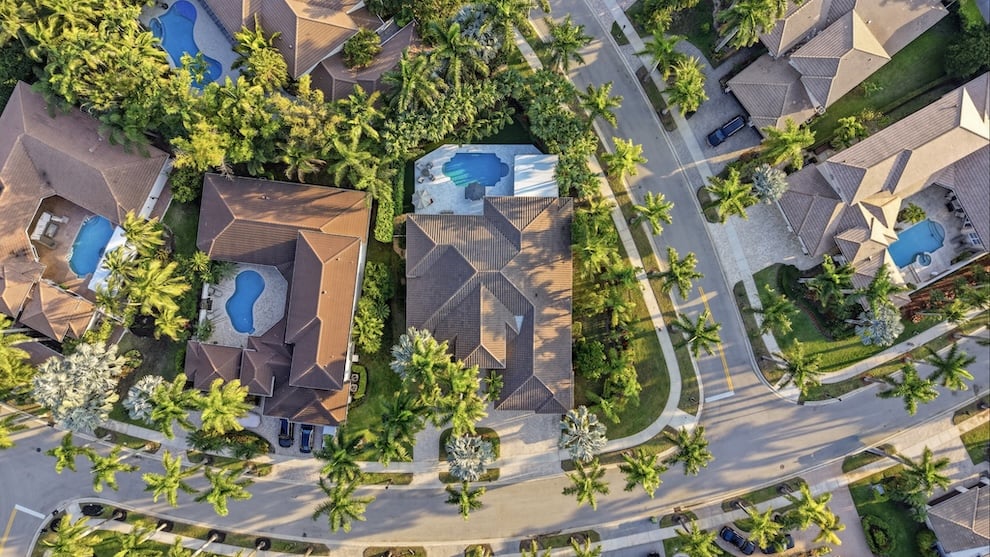
An old roof does not make your Weston home impossible to insure. It just leaves a big question hanging over your sale. Unanswered questions get expensive once a buyer, an insurance company and a lender are all racing the same closing date. That is the real problem. It is the calendar, not the tiles. Here is what happens when a seller waits.
We accept an offer. The buyer's inspector notices the roof is old. The insurance company asks for paperwork nobody has looked for. The buyer's insurance quote comes back with terms the lender will not approve. Now you are collecting roofing bids on a deadline, the buyer sees you are stuck, and every day that passes strengthens their position. At that point the roof is the negotiation. Your house is not.
If your roof is getting up there in age, start now. Not when you are under contract. Not when a buyer brings it up. Now.
- Find the permit. Pull the closed roofing permit and final inspection so the installation date is a documented fact and not a guess.
- Get the roof inspected this month. Depending on what insurance companies will want, that may be a roof certification, a four point inspection or a wind mitigation report. Your insurance agent can tell you which one applies.
- If the inspection says the roof is near the end, order the roof. Get written bids for the same scope of work, sign with your contractor and get in the permit line.
- Check your insurance path. Ask a licensed insurance professional to get real quotes on your specific property before we go to market.
- Then we price the house, with the facts already in hand.
A finished roof, or even a signed contract with a permit and a start date, turns your biggest question mark into a selling point. You pick the contractor. You pick the materials. You pick the timing. Once you are under contract, the buyer controls all three, because the buyer controls the deadline. Weston is in Broward County's High Velocity Hurricane Zone, which means our building requirements are stricter than most of the country. Replacing a roof here is not a weekend job. Once the old roof comes off, the wood underneath may need to be renailed to current code. If you have solar panels, solar water heating or gas vents on the roof, they have to be removed and reinstalled, and that takes its own permits. Tile and specialty materials can be on back order. Your HOA may need to approve the look. Then come the permits, the inspections and the final sign off. None of that is a problem if you start early. All of it is a problem if you start on day twelve of a buyer's inspection period.
Most roof conversations get muddy because four different questions get treated as one. Keep them separate.
- How old is the roof, on paper. Insurance companies want permits and invoices, not an estimate.
- How much life is left in it. Five years is the number that matters.
- What insurance is actually available. Not just the premium, but the deductible and the coverage, and whether a lender will accept it.
- What replacement would cost and how long it would take. Real bids, real permit timelines.
If you are buying, get written insurance quotes during your inspection period and send them to your loan officer to make sure the coverage satisfies the lender. Ask for the roof permits. Confirm the real installation date instead of accepting an estimate. Order whatever inspection your insurance company wants. And compare deductibles and roof coverage terms, not just the yearly premium. Most buyers here finance, so your insurance and your loan approval are tied together. Once the facts are on the table, this is a manageable conversation. A new roof helps with both insurance and presentation. A credit to the buyer lets them choose their own contractor, but it may not satisfy a lender that wants the work done before closing. Repositioning the price changes the math without fixing the insurance problem. An old roof does not have to cost you leverage. Ignoring it until closing week will. If you are thinking about selling in Weston, let's sit down now and look at your roof, your insurance and your timeline, while all of the choices are still your.